Anyone who has bought bullion online has watched the little clock in the corner of the cart tick down, with a note that the price refreshes when it reaches zero. Plenty of first-time buyers read that as a pressure tactic borrowed from airline websites. It is closer to the opposite. That timer is the visible edge of a hedging operation running quietly behind every well-run dealer, and once you see what it is doing, most of what feels arbitrary about buying metal on a screen starts to make sense.
A price lock is a contract, not a courtesy
When you confirm an order, the dealer stops treating your visit as browsing and starts treating it as a binding transaction. Dealer terms are blunt about this. The price is locked at the moment of order confirmation, the order stands as the final offer, and it cannot be renegotiated afterward because the market moved against you. You have agreed to buy a stated quantity of metal at a stated number, and the firm has agreed to deliver it.
That matters more than the paperwork suggests. A buyer who locks has, in that instant, taken the price risk off the dealer’s books and accepted it personally. Everything that follows, including the payment deadline and the cancellation terms, exists to make sure the transfer actually holds. It is worth reading those terms on any site you use before you need them, the same way you would read how the buying process works before your first order rather than during it.
How gold price locks work behind the counter
Dealers do not want a view on the gold price. A firm holding physical inventory is long metal whether it wants to be or not, and a firm carrying unfilled customer orders is short. The business lives on the spread between what it pays and what it receives, not on guessing direction, so the goal is to finish each session with neither position.
The tool is the futures market. Take a dealer holding five thousand ounces of inventory against three thousand ounces of open orders. That firm is net long two thousand ounces, and it offsets the exposure by shorting twenty COMEX gold contracts of one hundred ounces each. Physical and paper cancel out. If spot drops overnight, the loss on the shelf is matched by the gain on the short, and the doors open again in the morning. Dealers who do not hedge, or who are too small to trade futures at all, are the ones carried out by a single violent session.
Now drop your order into that machinery. The moment you lock, the hedge covering that particular parcel of metal is no longer needed, so it comes off. The firm has fixed its margin on your transaction and holds no further exposure to spot on it. Buyers rarely picture this step, and it is precisely why a lock cannot be casually undone. Unwinding your order sends the dealer back into the market to re-establish a position at whatever the price happens to be by then.
Why the quote has a clock on it
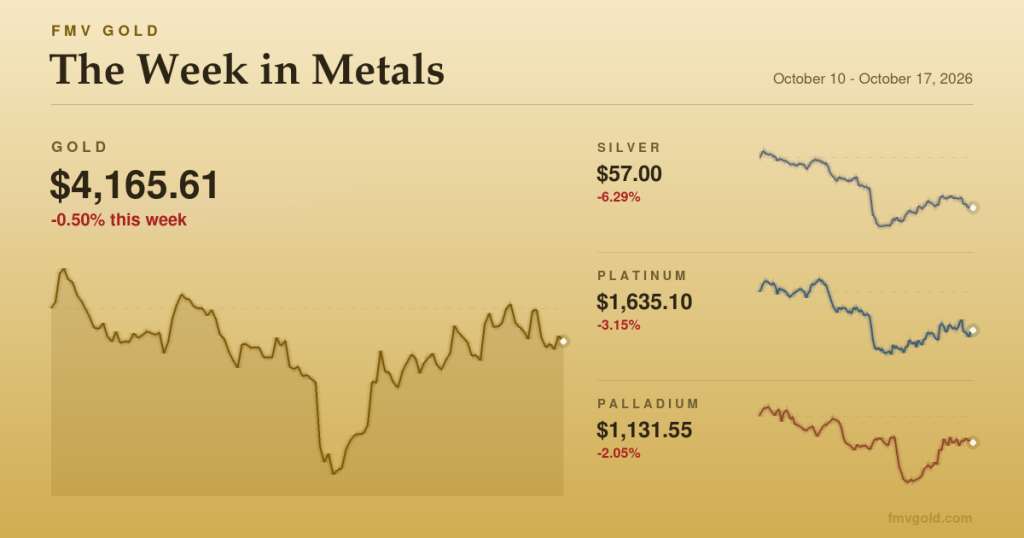
Spot is not a figure published once a day. It is derived from continuous trading in the nearest active COMEX contract, and it moves for as long as that market is open, which is very nearly around the clock. Gold futures run from Sunday evening at six Eastern through Friday afternoon at five, pausing for roughly an hour each day at the close. Between those bookends, the reference number underneath every product page is in motion, which is why the figures on a live market page never sit still for long.
A quote held open indefinitely would amount to a free option. The buyer could wait, watch, and return only if metal rallied, handing the dealer all of the downside and none of the upside. Capping the hold at a few minutes in the cart, then converting it into a firm commitment at checkout, is how a dealer avoids writing options it never charged for. Understanding how gold price locks work is mostly understanding that the clock is the price of certainty.
Market loss policies and the asymmetry inside them
The cancellation structure is remarkably consistent across the industry. Payment is due inside a set window, commonly about a day for a bank wire and a few business days for a check, and missing it counts as a breach rather than a change of heart. If you cancel or fail to pay and metal has fallen since you locked, you owe the difference between your locked price and the firm’s current ask, generally with a flat administrative fee on top. If metal has risen instead, there is no loss to recover, so no market loss charge applies.
Notice the asymmetry, because it is deliberate: any market gain on a cancelled order stays with the dealer. Viewed from the firm’s side, this follows directly from the hedge. It offsets your cancelled order at the current ask and passes along the deficit, having never been positioned to profit from your indecision. Viewed from yours, a lock is not a reservation you can abandon quietly. Lock when the money is ready to move, not while you are still deciding. Policies do vary in the details, so if you are comparing firms, the cancellation language belongs on the checklist alongside everything else in a dealer directory listing.
Weekends, gaps, and why Monday can look different
Friday afternoon to Sunday evening is the one long stretch when the hedging market is shut. Dealers handle it by estimating weekend sales and carrying an offsetting position into the Friday close, and larger wholesalers will sometimes make a weekend market at deliberately wider spreads so smaller firms have somewhere to lay off risk. That widening is not opportunism. It is the cost of quoting into a gap nobody can hedge through until the Sunday open, and it behaves much like the widening covered in our explainer on the bid-ask spread.
The practical consequence is that a Saturday order can behave differently from a Tuesday one. Some sites price normally and confirm on the open, some widen their numbers, and some pause certain products entirely until the market returns. If you are weighing a purchase over a weekend, it is worth a minute to learn how gold price locks work on that particular site, and whether the figure in front of you is live or a placeholder.
Buying with the clock in mind
- Stage the funds before you lock. The deadline starts running at confirmation, not when you get around to logging into your bank.
- Know what your payment method costs you. Wires and checks generally produce a better effective price than cards because the processing burden is lower, and they carry different deadlines.
- Do not lock while still shopping. Comparing two firms is free. Locking at both and walking away from one is not.
- Keep spot and premium separate in your head. A lock fixes your metal price, while the premium over spot is its own market, and premiums often move against spot rather than with it.
- Expect the same discipline when you sell. A buyback quote is a lock pointed the other direction, with its own window and its own expectation that the metal actually ships.
Widely recognized products make all of this easier, because a dealer can hedge and re-offset a common one-ounce coin such as a Gold American Eagle without much friction, and that liquidity tends to show up as tighter pricing and fewer surprises at checkout. Obscure items are harder to offset, which is one quiet reason their quotes can feel less accommodating.
None of this is unique to metals. Any dealer who quotes a firm price in a market that never stops moving has to decide how long that promise lasts and who pays if it breaks. What the bullion trade does is put the answer on the screen, in the form of a countdown and a paragraph of cancellation language that most buyers scroll past. The buyers who read it tend to be the ones who are never surprised, which is a decent working definition of the habits worth keeping in this business.