Anyone who has watched a dealer’s order page for a few months has noticed something strange. Spot climbs hard, and the finished coin costs less over metal than it did before. Spot collapses, and the coin stubbornly refuses to get cheap. The metal is doing one thing. The coin is doing something else entirely.
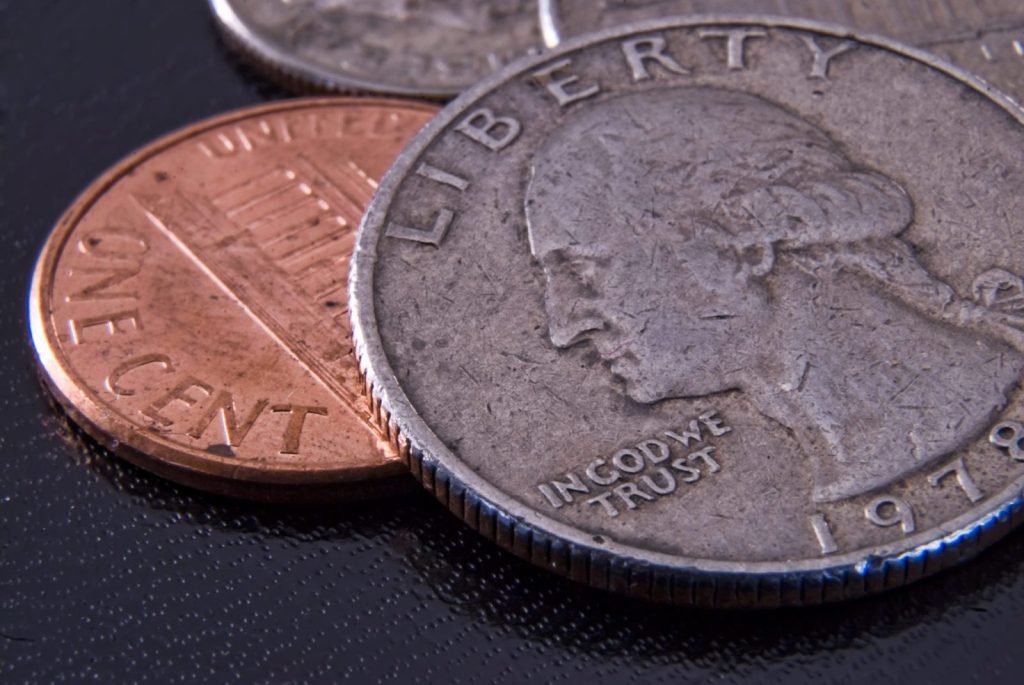
That gap has a name and a market of its own. The premium is what a struck coin or poured bar sells for above the value of the metal inside it, and it has its own supply, its own demand, and its own cycle. Understanding why coin premiums change is most of what separates a buyer who picks a decent moment from one who pays for the same ounce twice.
The premium is a separate price
Spot is the price of unfabricated metal in wholesale form. A coin is metal plus work: refining, blanking, striking, packaging, insured freight, and the margin of everyone who touched it on the way to a doorstep. Our explainer on what the premium over spot actually covers walks through those layers, and the how it works page shows where melt value sits in the stack.
The important part is that these two prices are set by different people for different reasons. Spot is set by futures traders, central banks, refiners, and industrial buyers. The premium is set by how many finished coins exist relative to how many people want one this week. Nothing forces them to move together, and quite often they move opposite each other.
Why coin premiums change when spot is rising
Start with arithmetic, because it does a lot of the work here. Striking, packaging, and shipping a one ounce coin costs roughly the same number of dollars whether the metal inside is worth twenty dollars or seventy. That fixed cost is a large percentage of a cheap ounce and a small percentage of an expensive one. A rally alone, with no change in behavior anywhere, mechanically shrinks the percentage premium.
Then behavior piles on. Rising prices pull coins out of closets, safes, and estates. People who bought years ago decide to take the win, and that flood of used metal lands in the same shops that sell new product. Random year coins from the secondary market compete directly with freshly minted ones, and secondary supply costs a dealer far less to acquire than a wholesale order from an authorized distributor.
Buyers get skittish at the same time. A position that cost twenty thousand dollars last year costs considerably more at a new high, and the marginal retail buyer either steps down to fractional sizes or waits. Dealers left holding inventory in a market with more sellers than buyers do the obvious thing and cut the markup.
Silver in 2026 illustrated all of this in about six months. The metal opened the year in the low seventies, ran to roughly $111 an ounce in late January on a wave of safe haven and industrial buying, then gave most of that back. By early September silver traded near $67 an ounce. Through that round trip the U.S. Mint’s bullion Silver Eagle sales fell month after month, and in May 2026 the Mint sold none at all, reported as the first blank month since the program began in 1986. Dealers were not short of coins. They were drowning in coins the public had handed back at the top, and premiums on ordinary silver sat near the low end of their historical range as a result.
Why premiums widen when spot falls
Now run it the other way. Sharp selloffs do not send retail buyers away. They bring them in, all at once, into a distribution system that cannot restock quickly.
March 2020 remains the cleanest example on record. Spot silver slid from about $17 to roughly $14.50 while the physical market went the opposite direction. Pre-1965 90 percent silver coins that had traded near 3 percent over spot were quoted above 70 percent over spot by late March. American Silver Eagle premiums moved from the high teens as a percentage to somewhere in the 60 to 75 percent range. Retail silver premiums roughly tripled at the peak.
The supply side simply stopped. Three major Swiss refiners near the Italian border suspended operations, South Africa shut its mining sector for three weeks, and the Royal Canadian Mint closed for two weeks in late March. Large dealers reported the heaviest order volume in their history with shipping delays running past twenty business days. Meanwhile the futures price was falling because leveraged funds were liquidating paper contracts to meet margin calls, which had almost nothing to do with the availability of an actual coin in an actual tube.
The pattern repeats at smaller scale. During the social media driven silver episode of early 2021, dealer shelves emptied and Silver Eagle premiums pushed past 50 percent at many retailers. After the April 2013 gold crash, Western selling met a wall of Asian bargain buying, and premiums over the London benchmark spiked in China and India sharply enough that India raised its gold import duty to 10 percent and imposed the so called 80/20 rule requiring dealers to re-export a fifth of every shipment. Our piece on premium spikes during shortages covers that dynamic in more depth.
The mint cannot just make more
One structural detail explains why these episodes last months rather than days. The U.S. Mint does not manufacture its own silver blanks. It buys planchets from outside vendors, and when those vendors ration, the Mint rations too, distributing Silver Eagles to Authorized Purchasers in weekly allocations rather than halting the program outright. The 2014 Silver Eagles launched on January 13 that year under exactly such a limited sales system, and allocation was not lifted until June 2, 2014, once blank supply had recovered and demand had cooled.
A retail panic can double demand in a week. The blank supply chain answers in quarters. That mismatch is the engine underneath every premium spike anyone has lived through.
What a buyer or seller can do with this
Track the premium as its own number, not as noise around spot. A quiet market with heavy secondary supply is when finished metal is cheapest relative to its melt value, and that is rarely when the headlines are exciting. Spot itself is easy enough to follow on our markets page.
- Count the round trip. What matters is the premium paid on the way in plus the premium given up on the way out. A coin bought at a shortage peak and sold in a calm market can lose real ground even if spot never moved. The buyback side is covered in our look at which coins are easiest to sell.
- Expect thin premiums to be temporary, and fat ones too. Both revert. Neither is a forecast about the metal price.
- Recognized government coins swing least. Widely traded sovereign issues such as American Silver Eagles tend to hold tighter spreads in both directions than generic rounds, because any shop can authenticate them on sight.
- Ask about buyback before you buy. Comparing what different dealers quote on both sides tells you more about the real cost of a product than the sticker premium alone.
None of this predicts where gold or silver goes next, and none of it is advice about whether to own either. It is a description of plumbing. Metal and manufactured coins are traded in two different markets that happen to share a name, and the difference between them widens exactly when everyone wants the same thing at the same time.