A buyer who checks the Mint’s catalog on a Tuesday and again on Thursday morning can find the same proof gold coin carrying a different price, even when gold itself barely moved in between. Nothing improper has happened. The United States Mint reprices its collector gold on a published schedule, against a published table, and that schedule answers to a calendar rather than to a live market feed.
The table is worth knowing about. It explains why Mint prices behave nothing like a dealer’s screen, and why the gap between the two opens and closes on a rhythm you can actually predict.
How the U.S. Mint prices its gold coins
The method dates to a Treasury notice effective January 12, 2009, adopted in the Mint’s own words “to mitigate the effect that fluctuating gold and platinum commodity costs has on the pricing of these products.” The metal panic of 2008 had made ad hoc repricing a poor fit for an institution that has to recover its minting, marketing, and distribution costs while selling into a market that can move several percent before lunch.
What the Mint adopted instead was an averaging window. The original policy used “the London Fix weekly average (average of the London Fix prices covering the previous Thursday a.m. Fix through the Wednesday a.m. Fix).” Each Wednesday the Mint applies that average to its pricing table, and any resulting change takes effect at 10 a.m. Eastern the following Thursday. The benchmark has since changed hands and mechanics, with the old London Fix giving way on March 20, 2015 to the electronically auctioned LBMA Gold Price administered by ICE Benchmark Administration, but the Mint’s approach survived the transition intact. Current Federal Register notices still state that “pricing can vary weekly dependent upon the London Bullion Market Association (LBMA) gold price weekly average,” and that prices for numismatic gold, platinum, and palladium products are “evaluated every Wednesday and modified as necessary.” The authority cited is 31 U.S.C. 5112(i)(4)(C).
The table itself is the part most buyers never see. The Mint publishes a pricing grid that carves the metal market into bands of fifty dollars. The 2026 gold grid starts at $2,000.00 to $2,049.99 and climbs in fifty dollar steps through $10,049.99, with a column for each product: the one ounce proof and uncirculated American Eagle, the fractional proof Eagles and the four coin set, the American Buffalo proof, American Liberty, commemorative gold, the Best of the Mint sets, and the Semiquincentennial gold proof. When the weekly average crosses from one band into the next, every product in that column steps up or down by its own fixed amount.
What the grid covers, and what it leaves out
This applies to collector product only. Numismatic gold, commemorative gold, platinum, and palladium all sit on the grid. The bullion American Eagle and American Buffalo do not, because the Mint does not sell bullion coins to the public at all. Those move through the authorized purchaser network at spot plus a mint-set manufacturer premium, then down through distribution, which is a different pricing world with different economics. Our piece on secondary market bullion walks through that channel in detail.
The practical upshot is that two coins struck from the same ounce of gold, in the same building, can reach a buyer through two entirely unrelated pricing systems. One is a Wednesday grid lookup. The other is a wholesale premium layered on a live quote.
A staircase, not a slope
Fifty dollar bands mean the Mint’s price is a step function. Gold can travel forty nine dollars inside a band and the catalog will not blink. Cross the boundary and the price moves by a set amount, all at once, on a Thursday morning. Dealers, who reprice continuously against the live market, produce a smooth curve. The Mint produces stairs.
That difference is the source of most of the confusion. A collector watching spot tick up through a quiet week may wonder why the Mint has not reacted, then find a change waiting on Thursday that seems disproportionate to anything that happened Wednesday. The change was not a reaction to Wednesday. It was the week’s average finally clearing a line.
The lag is the interesting part
Because the window looks backward and the change lands a day later, the Mint’s catalog always reflects metal prices from the recent past. In a rising market that lag runs in the buyer’s favor for a few days, since the catalog is still keyed to a lower weekly average while the live market has moved on. In a falling market it runs the other way, and a buyer pays against an average that the market has already left behind.
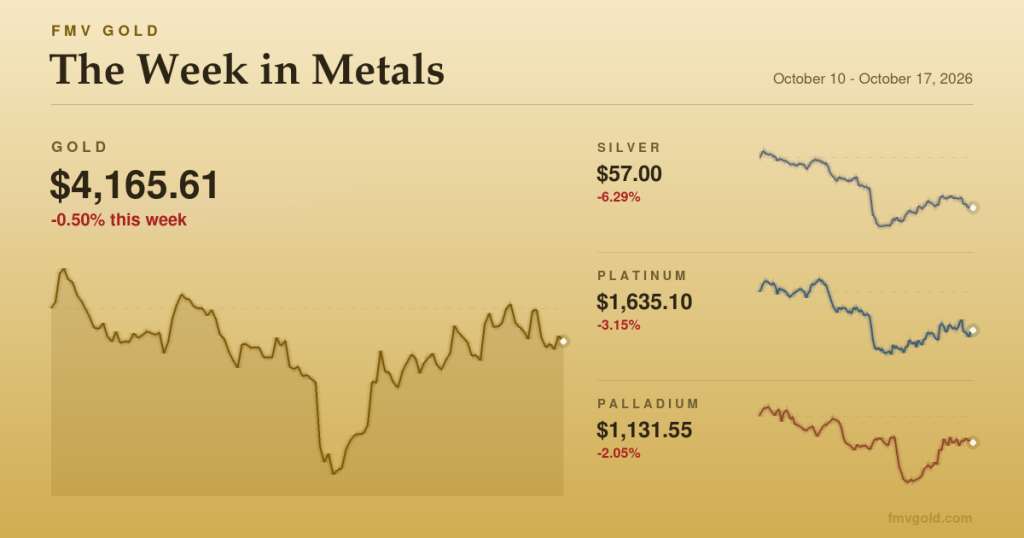
None of this is a strategy, and it is not an argument for timing anything. It is arithmetic, and it is the same arithmetic that makes a dealer’s quote expire in minutes while the Mint’s holds for a week. If that contrast interests you, our explainer on how price locks work covers the dealer side of the same problem, and the markets page tracks the underlying spot moves that feed both.
When the clockwork stops
Here is the honest caveat. The Wednesday and Thursday rhythm described above is the documented process, not an ironclad guarantee. Amid the heightened volatility of recent years, the Mint has at times stepped away from that steady cadence, pausing sales or pulling products from its online catalog while it conducts repricing reviews, and some of those adjustments have arrived without the advance Federal Register notice that once accompanied them.
Anyone planning a purchase around a release date should treat the grid as the Mint’s normal method rather than a promise about next Thursday. Check the current grid before ordering, and expect the possibility that a product goes temporarily unavailable in a fast market.
What the grid does not tell you
One last point, and it is the one that matters most for anybody thinking about value rather than checkout. The grid sets what the Mint asks. It says nothing about what a coin is worth afterward.
The moment an issue sells out or the year closes, its price is set by collectors and dealers trading among themselves, and the grid becomes a historical footnote. Some issues hold well above the metal on scarcity and demand. Others settle back toward the metal floor and sit there. Understanding the premium over spot matters more to the long run outcome than knowing which Thursday the catalog changed, and melt value remains the floor beneath any of it, as our how it works page and our rules of gold both lay out.
Still, knowing how the U.S. Mint prices its gold coins removes a small mystery from the process, and it puts an odd Thursday morning price change into a category most buyers find easier to live with: not a market signal, just a table doing what a table does. The same logic sits behind every American Gold Eagle that reaches a collector through the Mint’s front door.